What KYC means for Bitcoin and crypto businesses
Know Your Customer (KYC) is the process a regulated or otherwise in-scope business uses to establish who a customer is, understand relevant ownership and risk, and maintain an appropriate customer profile over time. In crypto, KYC is often discussed as an onboarding check, but a mature process continues after an account opens. It may include screening, refresh reviews, investigations and escalation when new information changes the risk picture.
The search data suggests an opportunity to answer a clear informational question: Semrush reports 720 U.S. monthly searches for “what is KYC in crypto” (KD 60) and 880 for “crypto KYC” (KD 64). In the U.K., those terms show 210 searches (KD 59) and 260 (KD 62), respectively. These terms are a better match for an educational guide than Bitcoin-only variations: “bitcoin KYC” returned only 50 U.S. monthly searches and KD 60. The article can still focus on Bitcoin exchanges and customer journeys while covering crypto KYC more broadly.
Why KYC matters to Bitcoin exchanges
Crypto businesses may onboard individuals, companies, merchants, institutional clients or other service providers. The information required and the level of review depend on the business model, the customer, the product and the law in each jurisdiction. KYC helps an organization form a reasoned view of the customer and identify when it needs more information or a closer review.
KYC is connected to but not identical with AML. KYC focuses on knowing and reviewing customers; AML refers to the wider set of controls designed to prevent and detect money laundering and related financial crime. A KYC program can support risk assessment and ongoing due diligence, while transaction monitoring examines activity for behavior that may need investigation. These controls should work together instead of being treated as separate checklist items.
For a Bitcoin exchange, useful questions include: Who is opening the account? Is the customer an individual or an entity? Who ultimately owns or controls the business? What products and activity are expected? Do screening results, adverse information or later account behavior require additional review? The answers should be captured in a process that can be explained and audited.
KYC and AML rules vary by jurisdiction
FATF sets international AML/CFT standards for virtual assets and virtual asset service providers, which countries implement through their own laws and supervisory systems. FATF’s July 2026 targeted update reported that 83% of surveyed jurisdictions had passed Travel Rule legislation, while another 11 jurisdictions said implementation was under way. The difference between a global standard and local legal requirements matters: a firm should map its own services and markets rather than assume one procedure satisfies every regulator. See the FATF 2026 update.
In the European Union, MiCA provides a harmonized framework for covered crypto-assets and crypto-asset service providers. The EU Transfer of Funds Regulation (EU) 2023/1113 also covers information accompanying certain crypto-asset transfers and applies from 30 December 2024. These rules affect different parts of a firm’s control environment: authorization and conduct on one side, and transfer information and traceability on the other. Consult the EUR-Lex MiCA overview and the Regulation 2023/1113 summary for the primary texts and summaries.
The exact legal obligations depend on jurisdiction and activity. This article explains operational KYC concepts and does not determine whether a particular company or product is legally in scope. Firms should validate current obligations with qualified counsel and their competent authorities.
A practical crypto KYC process
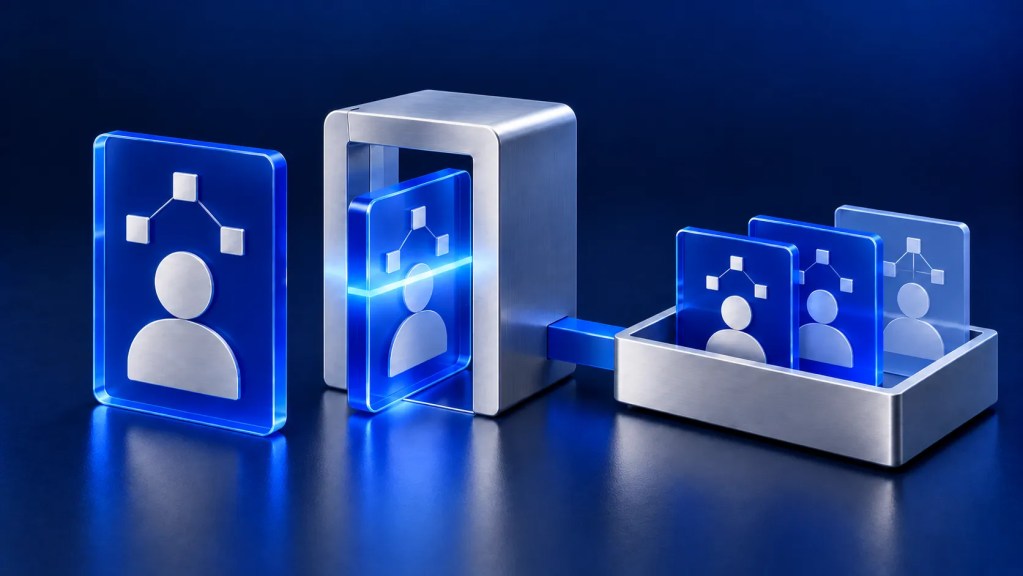
1.Identify the customer. Collect and verify information appropriate to the customer type and applicable rules. Distinguish individual customers from companies and other legal arrangements.
2.Understand ownership and control. For an entity, identify relevant beneficial owners, controllers and representatives according to the firm’s policy and legal requirements.
3.Screen for relevant risk. Check applicable sanctions, politically exposed person (PEP) and adverse media sources. Resolve potential matches carefully and document how they were assessed.
4.Understand the relationship. Record the purpose of the account, the products the customer plans to use, expected activity and other factors required by the firm’s risk assessment.
5.Apply a risk-based review. Use documented factors to decide whether standard checks are sufficient or further information and enhanced review are appropriate. Do not treat one data point as an automatic verdict.
6.Refresh the profile over time. Set review triggers or intervals in line with policy and applicable requirements. New ownership, screening results or activity patterns may mean the profile needs another look.
7.Keep an auditable record. Retain the information, sources, decisions, rationale and review outcomes needed to demonstrate how the process was applied, consistent with retention rules and privacy obligations.
What a KYC AI Agent can do

Customer research can require analysts to move between registries, screening tools, news sources and internal records. Repeating this work for every onboarding, periodic review or triggered case can slow decisions and make the quality of written findings vary from analyst to analyst. An AI agent can help by gathering relevant information, organizing evidence, identifying risk indicators and producing a structured report for a qualified reviewer.
Formica AI’s AI-Native KYC Agent is designed to investigate individuals and entities, search multiple risk sources, conduct sanctions, PEP and adverse media screening, and generate explainable, auditable reports. This can help analysts spend less time collecting evidence and more time assessing it. The final assessment and customer decision remain with the organization and its authorized personnel.
An effective KYC Agent workflow should make its scope clear: what sources were checked, when they were checked, which findings are relevant, what uncertainty remains and what a human reviewer needs to decide. Analysts should be able to review supporting evidence, distinguish confirmed matches from possible matches, correct errors and document the final outcome. These practices help keep automation useful and accountable.
How KYC and fraud prevention work together
KYC and fraud controls are strongest when information can flow into the right review at the right time. If monitoring identifies activity that differs from a customer’s established pattern, the investigator may need current customer information, ownership context or recent screening results. If an onboarding review identifies heightened risk, the business may set appropriate monitoring or review triggers. The specific decisions should follow the firm’s policies and applicable law.
Formica AI offers a connected route from customer investigation through activity review: use the AI-Native KYC Agent for customer and entity research, and Transaction Monitoring to evaluate transactions and behavior with rules and AI-based prediction. The broader AML & KYC solution page provides context on screening and compliance workflows.
This does not mean a KYC Agent traces Bitcoin wallets or replaces blockchain analytics. Customer due diligence and on-chain intelligence are distinct capabilities. A business should verify which data a tool uses, what it produces and how those outputs fit into its overall program.
Common KYC mistakes to avoid
•Treating KYC as a one-time event. Customer information and risk can change; define proportionate refresh and event-driven review processes.
•Relying on a name match alone. Potential sanctions or PEP matches need careful resolution using available identifiers and documented procedures.
•Collecting more information without a purpose. Define why each data element is needed, who can access it and how long it should be retained under applicable privacy and retention requirements.
•Using automation without review controls. Set clear boundaries for the agent, require human review where appropriate and preserve evidence and decision rationale.
•Confusing KYC with wallet analytics. KYC concerns customer identity and risk assessment; wallet and blockchain intelligence are separate tools and data sources.
A practical way to evaluate KYC automation
Before adopting a KYC Agent, compliance and operations teams can define a small set of measurable questions. How much analyst time goes to repetitive source gathering? How consistently do reports capture evidence and uncertainty? Can reviewers see where a finding came from? Does the process reduce avoidable back-and-forth without lowering the quality of decisions? How are false matches and source errors corrected? A controlled evaluation can compare the current process with an assisted workflow using representative cases and clear human review.
The goal is to make customer research faster and more consistent while preserving the organization’s judgment. Automation should help teams focus on the cases that need expertise, not obscure how an outcome was reached.
Make crypto KYC easier to review
Bitcoin and crypto businesses need KYC processes that can scale with customer growth and adapt to local requirements. A clear workflow establishes identity, assesses relevant risks, refreshes customer context and records why a decision was made. Formica’s AI-Native KYC Agent supports customer and entity research with structured, explainable reports for review. Teams can also explore the connected AML & KYC solution and Transaction Monitoring capabilities.
Frequently asked questions
What is KYC in crypto?
KYC in crypto is the process of identifying and reviewing customers of an in-scope crypto business, understanding relevant ownership and risk, screening applicable sources and keeping customer information current according to policy and law.
Do Bitcoin exchanges need KYC?
Requirements vary by jurisdiction, activity and customer relationship. Many regulated crypto service providers have customer due diligence obligations, but businesses should confirm their specific legal scope with qualified counsel and regulators.
What is the difference between KYC and AML?
KYC is a customer identification and due diligence process. AML is the broader framework of policies and controls to prevent, detect and respond to money laundering and related financial crime.
What does a KYC Agent do?
A KYC Agent can help research individuals and entities across relevant sources, organize findings and produce structured reports for review. The business remains responsible for its policies, decisions and compliance obligations.
Can a KYC Agent screen Bitcoin wallets?
Customer KYC and wallet or blockchain analytics are distinct capabilities. Confirm whether a provider supports wallet screening or on-chain analysis before relying on it for those tasks.
What is the Travel Rule for crypto?
The Travel Rule concerns information that must accompany certain transfers between virtual asset service providers under applicable local law. Scope and implementation vary. In the EU, Regulation (EU) 2023/1113 applies from 30 December 2024.
Support more consistent crypto KYC reviews
Formica AI’s AI-Native KYC Agent helps compliance teams research individuals and entities and review structured findings. Explore the product or request a demo to discuss your KYC workflow.
Explore Formica AI Transaction Monitoring | Discover AI-Native KYC | Request a demo